How to Invest Inherited Money in India: A Step-by-Step Plan
How to invest inherited money in India: what to confirm first, the Two-Number Rule for tax cost, and how to plan if you are a widow or a first-time investor.

Ckredence Wealth |October 13, 2026
Inherited money in India should not be invested on day one. Confirm what you hold, clear what is owed, and record what each asset cost the person who left it to you. Only then decide where it goes, because rushing that step is hardest to undo.
Consider a woman in Surat whose father left her shares in demat, units in two mutual fund folios, a bank balance and a flat. Or a widow in her late fifties who finds that her husband handled every investment. Both face the same decisions, in the same order.
TL; DR
Do not invest inherited money until the paperwork, liabilities and income needs are clear.
India has no inheritance tax, but tax arises on sale, measured from the original owner's cost.
The Two-Number Rule: record each asset's value today and its inherited cost.
Decide by purpose and time horizon, not by product name.
Holdings spread across several firms are easier to judge on one statement.
A widow's first plan should answer one question: what regular income does the household need?
Inherited a portfolio you did not build? We will read it with you and say plainly what we see.
| → Get a second opinion |
Should You Invest Inherited Money Straight Away in India?
No, hold it in a low-risk, accessible form until you know what you own, what is owed and what you need it for. The assumption is that idle money is lost money. The reality is that a rushed first allocation can cost more than weeks of patience.
Take a Surat textile trader's daughter who inherits a large stock holding and a bank balance in the same month. Selling the shares, or buying a flat with the cash, can both wait. Our guide to surplus money that should not sit idle or be rushed makes the same point for business windfalls.
📊 23% Only this share of women who have already inherited have structured plans. Among those who expect to inherit, 77% have begun planning. *Source: Outlook Money, on Barclays Private Bank's "The Ownership Shift" - as of 20 August 2026* |
What Should You Do First When You Inherit Money in India?
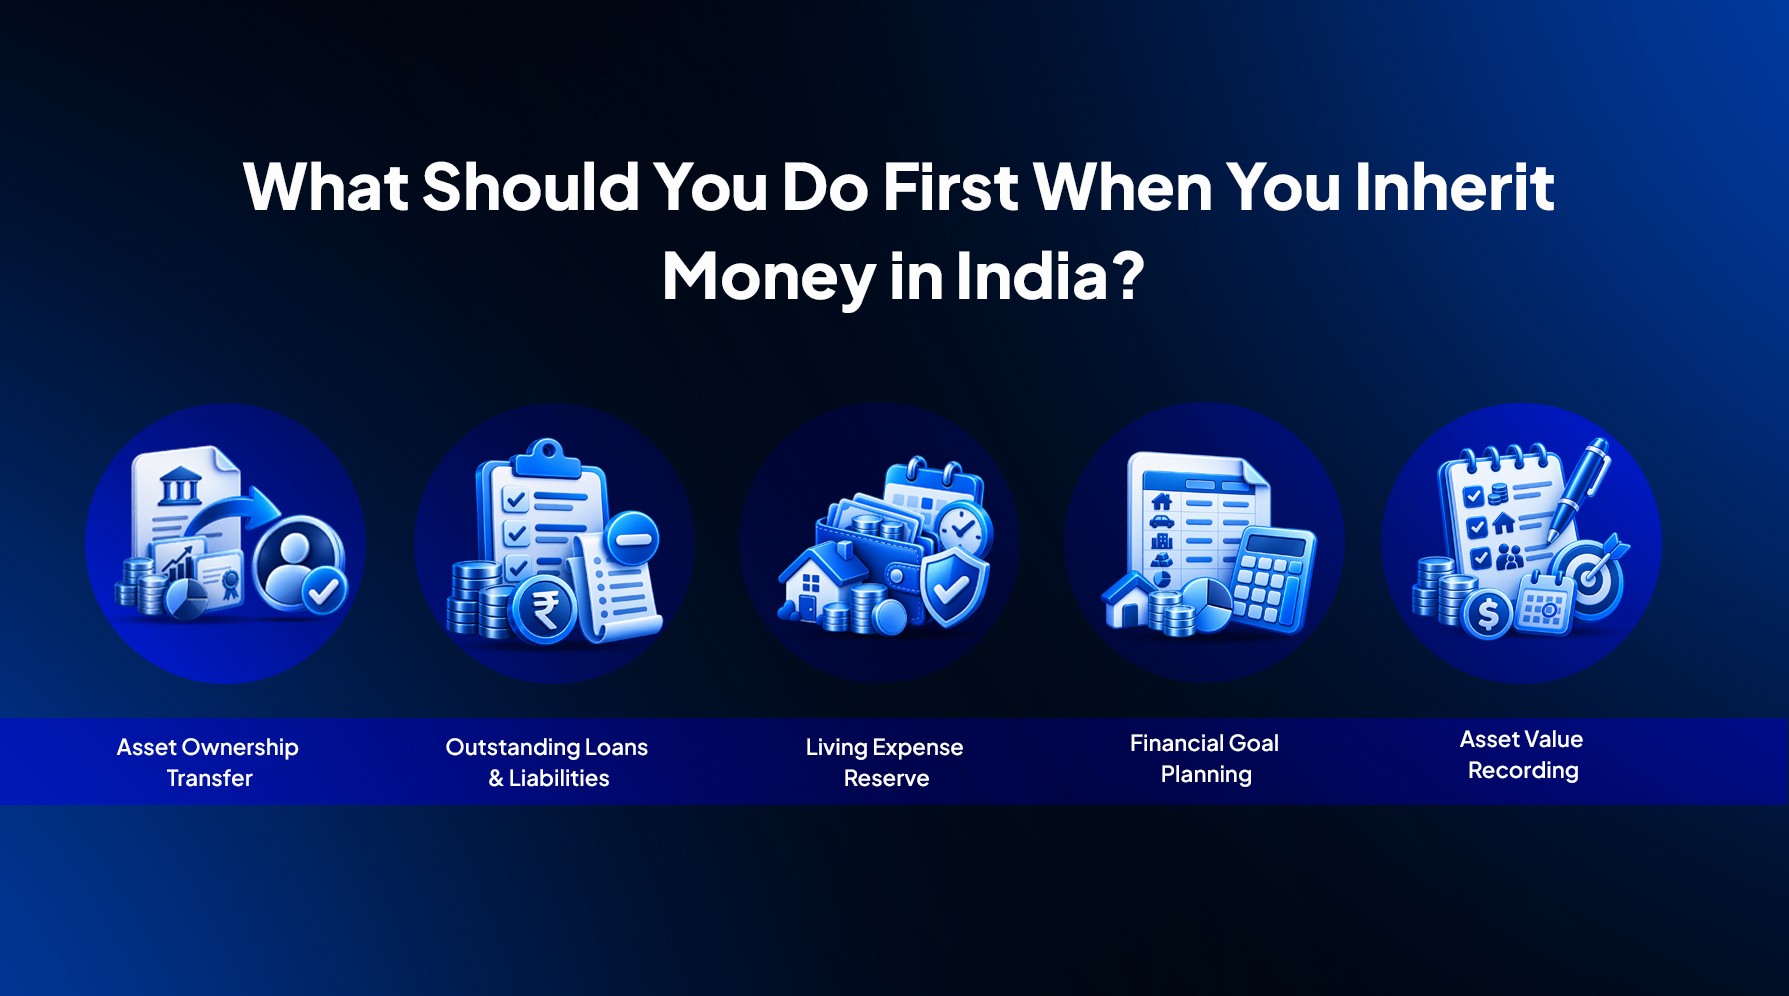
Work through five steps in order, because each one changes the next.
Confirm what has transferred. Check that shares, units and accounts are in your name, not the deceased's.
List what is owed. Loans and pending dues against the estate come out before anything is invested.
Set aside living costs for a period you are comfortable with, in an account you can reach.
Write down what the money is for. Income, a dated goal, or something to leave to your children.
Record the two numbers for every asset, as the next section shows.
The paperwork has also become lighter. SEBI's July 2026 framework raised the simplified limit to ₹30 lakh for demat and ₹10 lakh for physical securities. It also dropped mandatory probate in that route and set a 21-day processing limit (Outlook Business, 24 July 2026). Confirm the transmission steps with your depository participant or fund house.
What Is the Two-Number Rule for Inherited Investments in India?
Every inherited asset has two numbers: its worth today, and what the tax rules treat you as having paid. The first is what you have. The second decides what selling costs you.
India has no inheritance tax, so receiving the asset is not taxed. On sale, the gain runs from the original owner's cost, and the holding period starts from their purchase date, as Angel One explains (March 2025). The rule sits in Section 49(1) of the Income Tax Act, 1961, so confirm the equivalent provision under the new Act with your CA.
Asset (illustrative) | Value today | Inherited cost | Gain if sold today |
Listed shares | ₹35 lakh | ₹10 lakh | ₹25 lakh |
Equity fund units | ₹12 lakh | ₹8 lakh | ₹4 lakh |
These figures are arithmetic to show how the rule works. They are not a projection or an indication of what any portfolio will earn. Past performance is not indicative of future results.
A ₹35 lakh inheritance can carry a ₹25 lakh gain not yet realised. Rates differ by asset and holding period, so see taxation on mutual funds and PMS and capital gains on a property sale.
Put your inherited holdings on one page
Share your statements and we will build the two-number list with you, asset by asset.
Where Should You Invest Inheritance Money in India Once the Basics Are Done?
Decide by purpose and time horizon, not by product name. Money needed within a few years belongs in low-volatility holdings. Money for distant goals can carry equity risk, and income needs set the mix.
Purpose | Time horizon | Question to ask |
Living costs and reserve | Next year | Can I withdraw without a penalty? |
Planned spending, such as a home | One to five years | What if markets fall just before I need it? |
Long-term growth | Five years or more | Can I hold through a fall I have named in advance? |
Regular income | Ongoing | What does it pay, and what does it cost me? |
Our guide to asset allocation covers the split, and where to invest when FD rates fall covers the low-volatility end. For larger sums, how to invest ₹50 lakh walks through the trade-offs. PMS starts at ₹50 lakh under SEBI rules.
How Do You Consolidate Inherited Investments Spread Across Several Firms?
Start with one list, then judge the holdings as a single portfolio. Inherited money often sits across a broker, two fund houses and a bank, so duplication and concentration stay invisible until everything is side by side.
A consolidated account statement from the depositories and fund registrars shows demat and fund holdings across firms in one document. Then ask a SEBI-registered investment adviser to review them together. What we see is that heirs rarely know which holding matters most, because nobody ranked them.
How Should a Widow Plan Money After a Husband's Death in India?
Start with income, not growth. A widow's first plan asks what regular income the household needs, and which assets can supply it without a forced sale.
Find out what stands in his name alone, and which accounts have a nominee or joint holder.
Do not sign anything under pressure. Be cautious of anyone who arrives with a product before asking about your needs.
Choose a fee-based adviser, paid by you and not by the products. Our guide to choosing an adviser as a woman investor explains how.
⚠️ Risk to understand Long-lock-in products sold in the first weeks of a bereavement are hard to leave. Take a second opinion before committing capital. |
Who Should Not Follow This Plan?
Anyone whose estate is disputed. Wait for legal clarity before investing contested assets.
Anyone who needs a will, probate or trust drafted. Ckredence coordinates the portfolio side, as in family office planning. A lawyer handles the documents.
Anyone seeking a quick tip or promised returns. No registered adviser can give either.
Conclusion
The next decision is the order of your decisions, not the product. Confirm what you hold, record the two numbers, name the purpose, and invest last. A second pair of eyes at that point costs little.
Tell us what you have inherited and what you need it to do. We will say whether we are the right fit.
FAQs
How to manage inherited wealth as a first-time investor?
Confirm what you hold and what is owed, then write down what the money is for. Keep living costs in an accessible account, and match each remaining amount to a purpose and time horizon. A SEBI-registered adviser paid by you can review the plan before you commit capital.
What to do with inheritance money?
Do not spend or invest it at once. Confirm the assets are in your name, list liabilities, record each asset's value today and its inherited cost, and then decide by purpose. A few weeks of patience avoids most irreversible mistakes.
Is inherited money taxable in India?
India has no inheritance tax or estate duty, so receiving assets is not taxed. Tax applies when you sell, with the gain measured from the original owner's cost and holding period. Income earned from the assets afterwards is also taxable.
How can a wealth manager help consolidate inherited assets spread across multiple financial institutions after a succession event?
A wealth manager gathers statements from each firm and lists every holding with its value and inherited cost. The manager then reviews them as one portfolio, which shows duplication and concentration that separate statements hide.